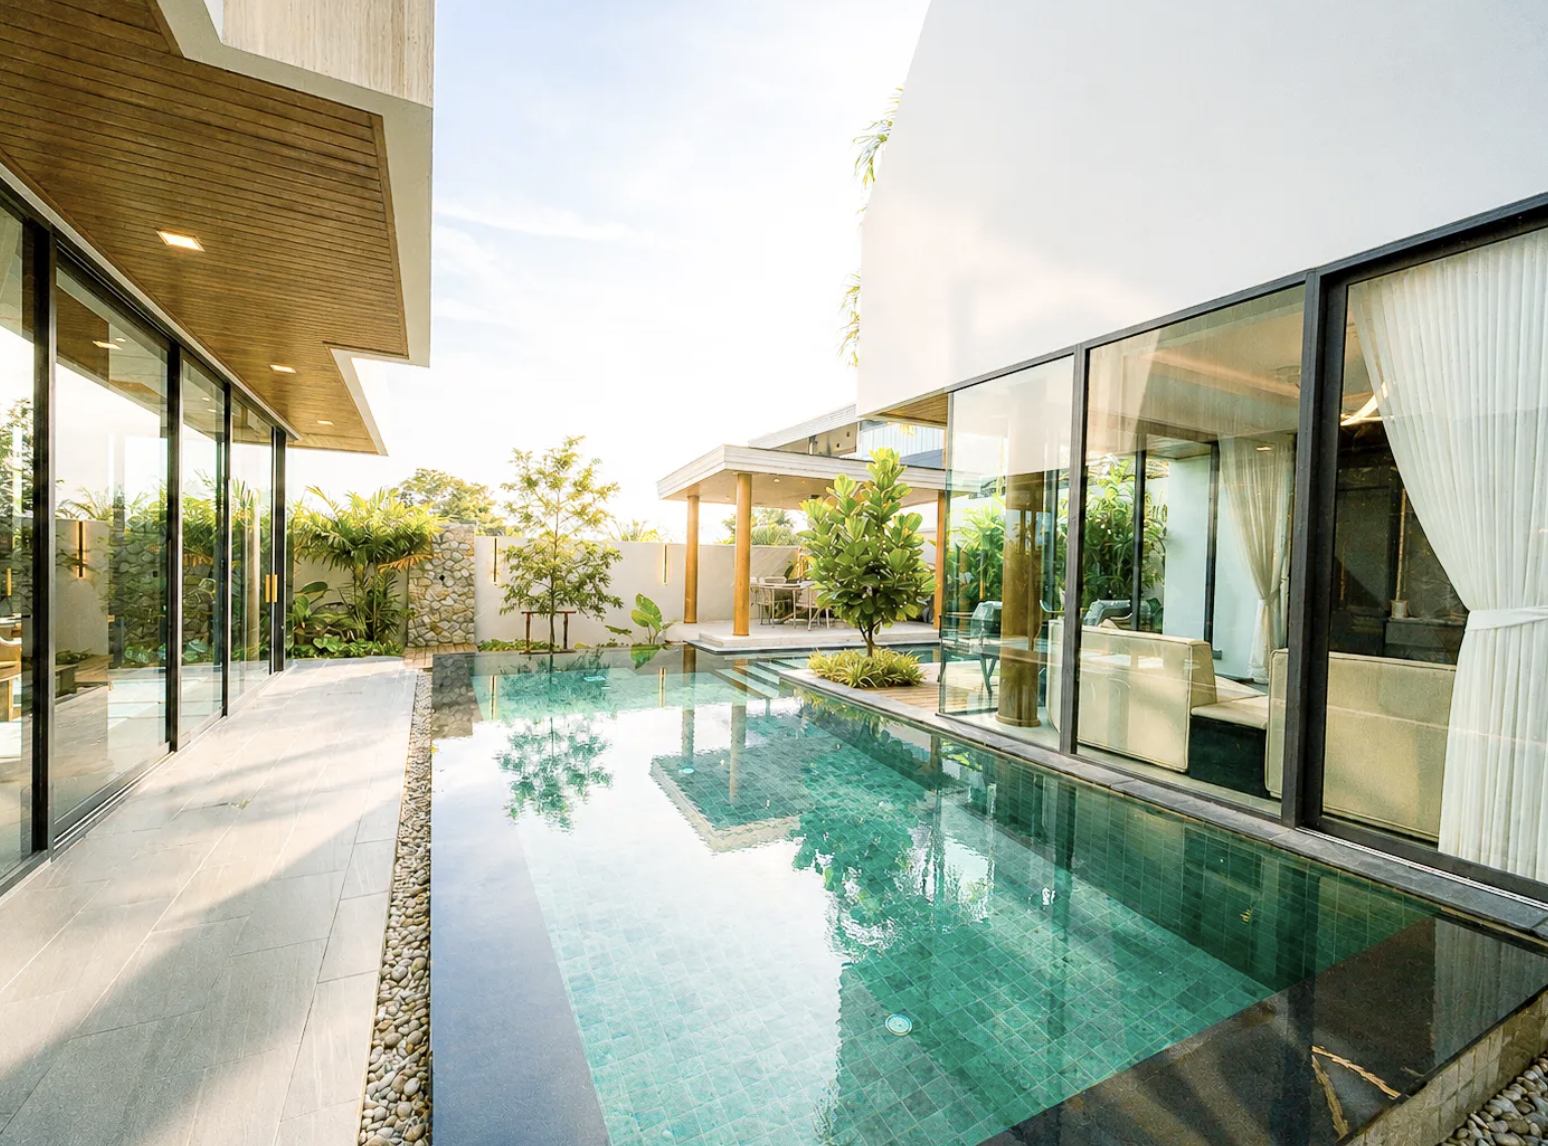
An exceptional private pool villa in Rawai, Phuket, offering beautiful sea and greenery views, asking $1.1M
Owning a Phuket property does not make you a Thai taxpayer. Spending enough days in Thailand does. Here is where the line sits, what changed in 2024, and why the IRS still has the final say on your worldwide income.
By Peter Tumbas · Berkshire Hathaway HomeServices New England Properties · phuketforamericans.com
Most Americans buying in Phuket assume tax is a two-line question: the property is in Thailand, so Thailand taxes it, and the IRS gets its usual share. In practice, the answer turns on a day count. A buyer who visits for the winter season and a buyer who lives in Phuket year-round are in different tax positions even if they own identical condos. This article explains how Thai tax residency is determined, what the 2024 foreign income change did, and how the US side of the equation fits. It builds on the filing obligations in Phuket for Americans' FBAR and FATCA guide and the owner-level income rules in its Schedule E rental income guide.
Thailand treats a person as a tax resident when they are physically present in the country for 180 days or more in a calendar year. The Thai tax year is the calendar year. The test counts days of presence. It does not ask what visa you hold, where you consider home to be, or whether you own property.
For a US reader, the closest comparison is the IRS substantial presence test, which is also a day-count test. The difference is that the IRS test uses a weighted three-year formula, while the Thai test is a simple count for the single calendar year. A buyer who spends 150 days in Phuket each year is generally not a Thai tax resident. A buyer who crosses 180 days in a year is, for that year, even if they were not one the year before.
Because the test is applied year by year, borderline years deserve care. Keep passport stamps, flight records, and an informal log of travel dates, and ask your Thai tax adviser how arrival and departure days are counted in your situation. Exceeding the threshold by a few days can change the tax treatment of an entire year.
The residency line matters because it changes the scope of Thai tax. Thai-sourced income is generally taxable in Thailand regardless of residency, and that includes rent from a Phuket property. A Thai tax resident is additionally exposed on foreign-sourced income that is brought into Thailand. Thai personal income tax uses progressive rates, rising to a top rate of 35%.
| Income Type | Non-Resident (Under 180 Days) | Thai Tax Resident (180+ Days) |
|---|---|---|
| Rent from a Phuket property | Thai-sourced, taxable in Thailand, usually through withholding | Thai-sourced, taxable in Thailand, reported on an annual return |
| US salary, pension, dividends | Generally outside Thai tax | Potentially taxable if brought into Thailand |
| US investment gains | Generally outside Thai tax | Potentially taxable if brought into Thailand |
| Money earned before 2024 and brought in later | Generally outside Thai tax | Generally treated differently from post-2023 income, with records required |
| US tax on all of the above | Worldwide income, reported to the IRS | Worldwide income, reported to the IRS |
Before 2024, a common planning approach was to earn income abroad in one year and bring it into Thailand in a later year, in which case it was generally not taxed in Thailand. From 1 January 2024, a Thai tax resident's foreign-sourced income that is brought into Thailand can be taxed regardless of the year in which it was earned. The old timing strategy no longer works for income earned in 2024 and later.
Two practical points follow. First, what matters is the movement of funds into Thailand, so the source and timing of transfers should be documented. Second, money earned before 2024 is generally treated differently from newer income, which makes dated bank statements and clear account histories valuable if you hold pre-2024 savings. Rules and official interpretations in this area have been revised since 2024, so confirm the current position with a Thai tax adviser before moving a large sum.
The LTR Visa (Long-Term Resident Visa) is an immigration status, and it has no minimum stay requirement. Holding one does not make you a Thai tax resident, and spending 180 days under any visa does. For LTR holders in the Wealthy Global Citizen, Wealthy Pensioner, and Work-from-Thailand Professional categories who do become Thai tax residents, the programme provides a Thai income tax exemption on foreign-sourced income brought into Thailand. Highly Skilled Professionals receive a flat 17% rate on Thai-sourced employment income instead. The full category rules are in Phuket for Americans' LTR Visa guide.
Typical profile: Winter-season visitor, rental investor, or second-home owner.
Typical profile: Retiree, remote professional, or LTR Visa holder living in Phuket.
US citizens are taxed on worldwide income wherever they live. The US-Thailand tax treaty exists to reduce double taxation, but it contains a saving clause that preserves the right of the United States to tax its own citizens as if the treaty did not apply, with limited exceptions. For most Americans the working tool is the Foreign Tax Credit, which lets Thai tax paid on income be credited against the US tax owed on the same income.
Two limits apply. The credit is generally capped at the US tax attributable to the foreign income, and the classification and sourcing of each type of income, such as wages, pension, dividends, and rent, affect how much credit is available. Some earned income can alternatively be excluded under the Foreign Earned Income Exclusion, which has its own eligibility tests. The right combination depends on income mix, so it needs to be modelled by a US tax attorney or CPA with international experience before you decide how many days to spend in Thailand.
Reporting does not change with residency. FBAR and FATCA obligations apply to Thai bank accounts above their thresholds whether or not you are a Thai tax resident, as covered in the FBAR and FATCA guide. When you eventually sell, the gain is taxed in both countries and sorted out through the credit, as explained in the guide to selling Phuket property as an American.
Submit a private inquiry and Peter will connect you with vetted advisers who can model Thai residency and your US tax position before you commit to a day count. Referral service, no cost to the buyer, no obligation.
Submit a Private Inquiry 412-225-0598 | petertumbas@bhhsne.comWhen does an American become a Thai tax resident?
Thailand treats a person as a tax resident when they are physically present in the country for 180 days or more in a calendar year. The test counts days of presence, not the visa you hold and not whether you own property. An American who owns a Phuket condo but spends fewer than 180 days a year in Thailand is generally not a Thai tax resident. Track your days with passport stamps and travel records, since borderline years are where disputes arise.
What is the 2024 Thai foreign income remittance rule?
From 1 January 2024, a Thai tax resident's foreign-sourced income that is brought into Thailand may be taxed regardless of the year it was earned. Before 2024, income earned abroad and brought in during a later calendar year was generally not taxed. The change affects Americans who live in Thailand for 180 days or more and move US salary, pension, dividends, or gains into a Thai account. Income earned before 2024 is generally treated differently, so keep records of when funds were earned.
Does the LTR Visa make me a Thai tax resident?
No. The LTR Visa is an immigration status with no minimum stay requirement, so it does not by itself create tax residency. Residency depends on spending 180 days or more in Thailand in a calendar year. For holders of qualifying LTR categories who do become Thai tax residents, the programme provides a Thai income tax exemption on foreign-sourced income brought into Thailand. That benefit reduces Thai tax only, and it does not change what an American owes the United States.
Does the US-Thailand tax treaty stop the IRS from taxing me?
No. US citizens are taxed on worldwide income wherever they live, and the treaty contains a saving clause that preserves the right of the United States to tax its own citizens. The treaty and the Foreign Tax Credit mainly reduce double taxation, so Thai tax paid can generally be credited against US tax on the same income. The result depends on how each type of income is classified and sourced, so have a US tax attorney with international experience model your situation.
Do I owe Thai tax if I only own a Phuket condo and rent it out?
Rent from a Thai property is Thai-sourced, so it can be taxed in Thailand whether or not you are a Thai tax resident. A non-resident owner typically has withholding applied through the property manager or tenant, while a resident files an annual Thai return. You also report the same rent to the IRS, usually on Schedule E, and may claim a credit for Thai tax paid. Owning the property does not by itself make you a Thai tax resident.
Do I need a Thai tax adviser and a US tax attorney?
If you plan to spend 180 days or more in Thailand, yes. A Thai tax adviser handles residency, remittance, and Thai filing questions, while a US tax attorney or CPA with international experience handles the Foreign Tax Credit, treaty position, and reporting such as FBAR and FATCA. Peter Tumbas is a Connecticut real estate professional and is not a tax adviser in either country. Through Phuket for Americans he can introduce vetted advisers as a no-cost referral service.
Peter built phuketforamericans.com to give American buyers the tax and legal context that developer marketing rarely discloses. He is not licensed in Thailand and is not a tax adviser or attorney in either country. All introductions to Thai and US advisers are made as a referral service at no cost to the buyer. More about Peter
Related reading: FBAR and FATCA · Rental income and the IRS · Retiring in Phuket
Peter responds to every inquiry personally within 48 hours.
Submit an Inquiry →